Bitcoin Slips Below $80K as CME Options Overtake Deribit: The Institutional Volatility Regime Has Arrived
2026-10-29, FP360 — Bitcoin slid 2.08% to $79,977 as spot bitcoin ETF options volume smashed records and CME open interest flipped Deribit for the first time, signaling that institutional hedging desks now dictate price action. The move lower is not a retail panic; it is a structural handoff from crypto-native leverage to regulated derivatives, and the market is repricing volatility accordingly.
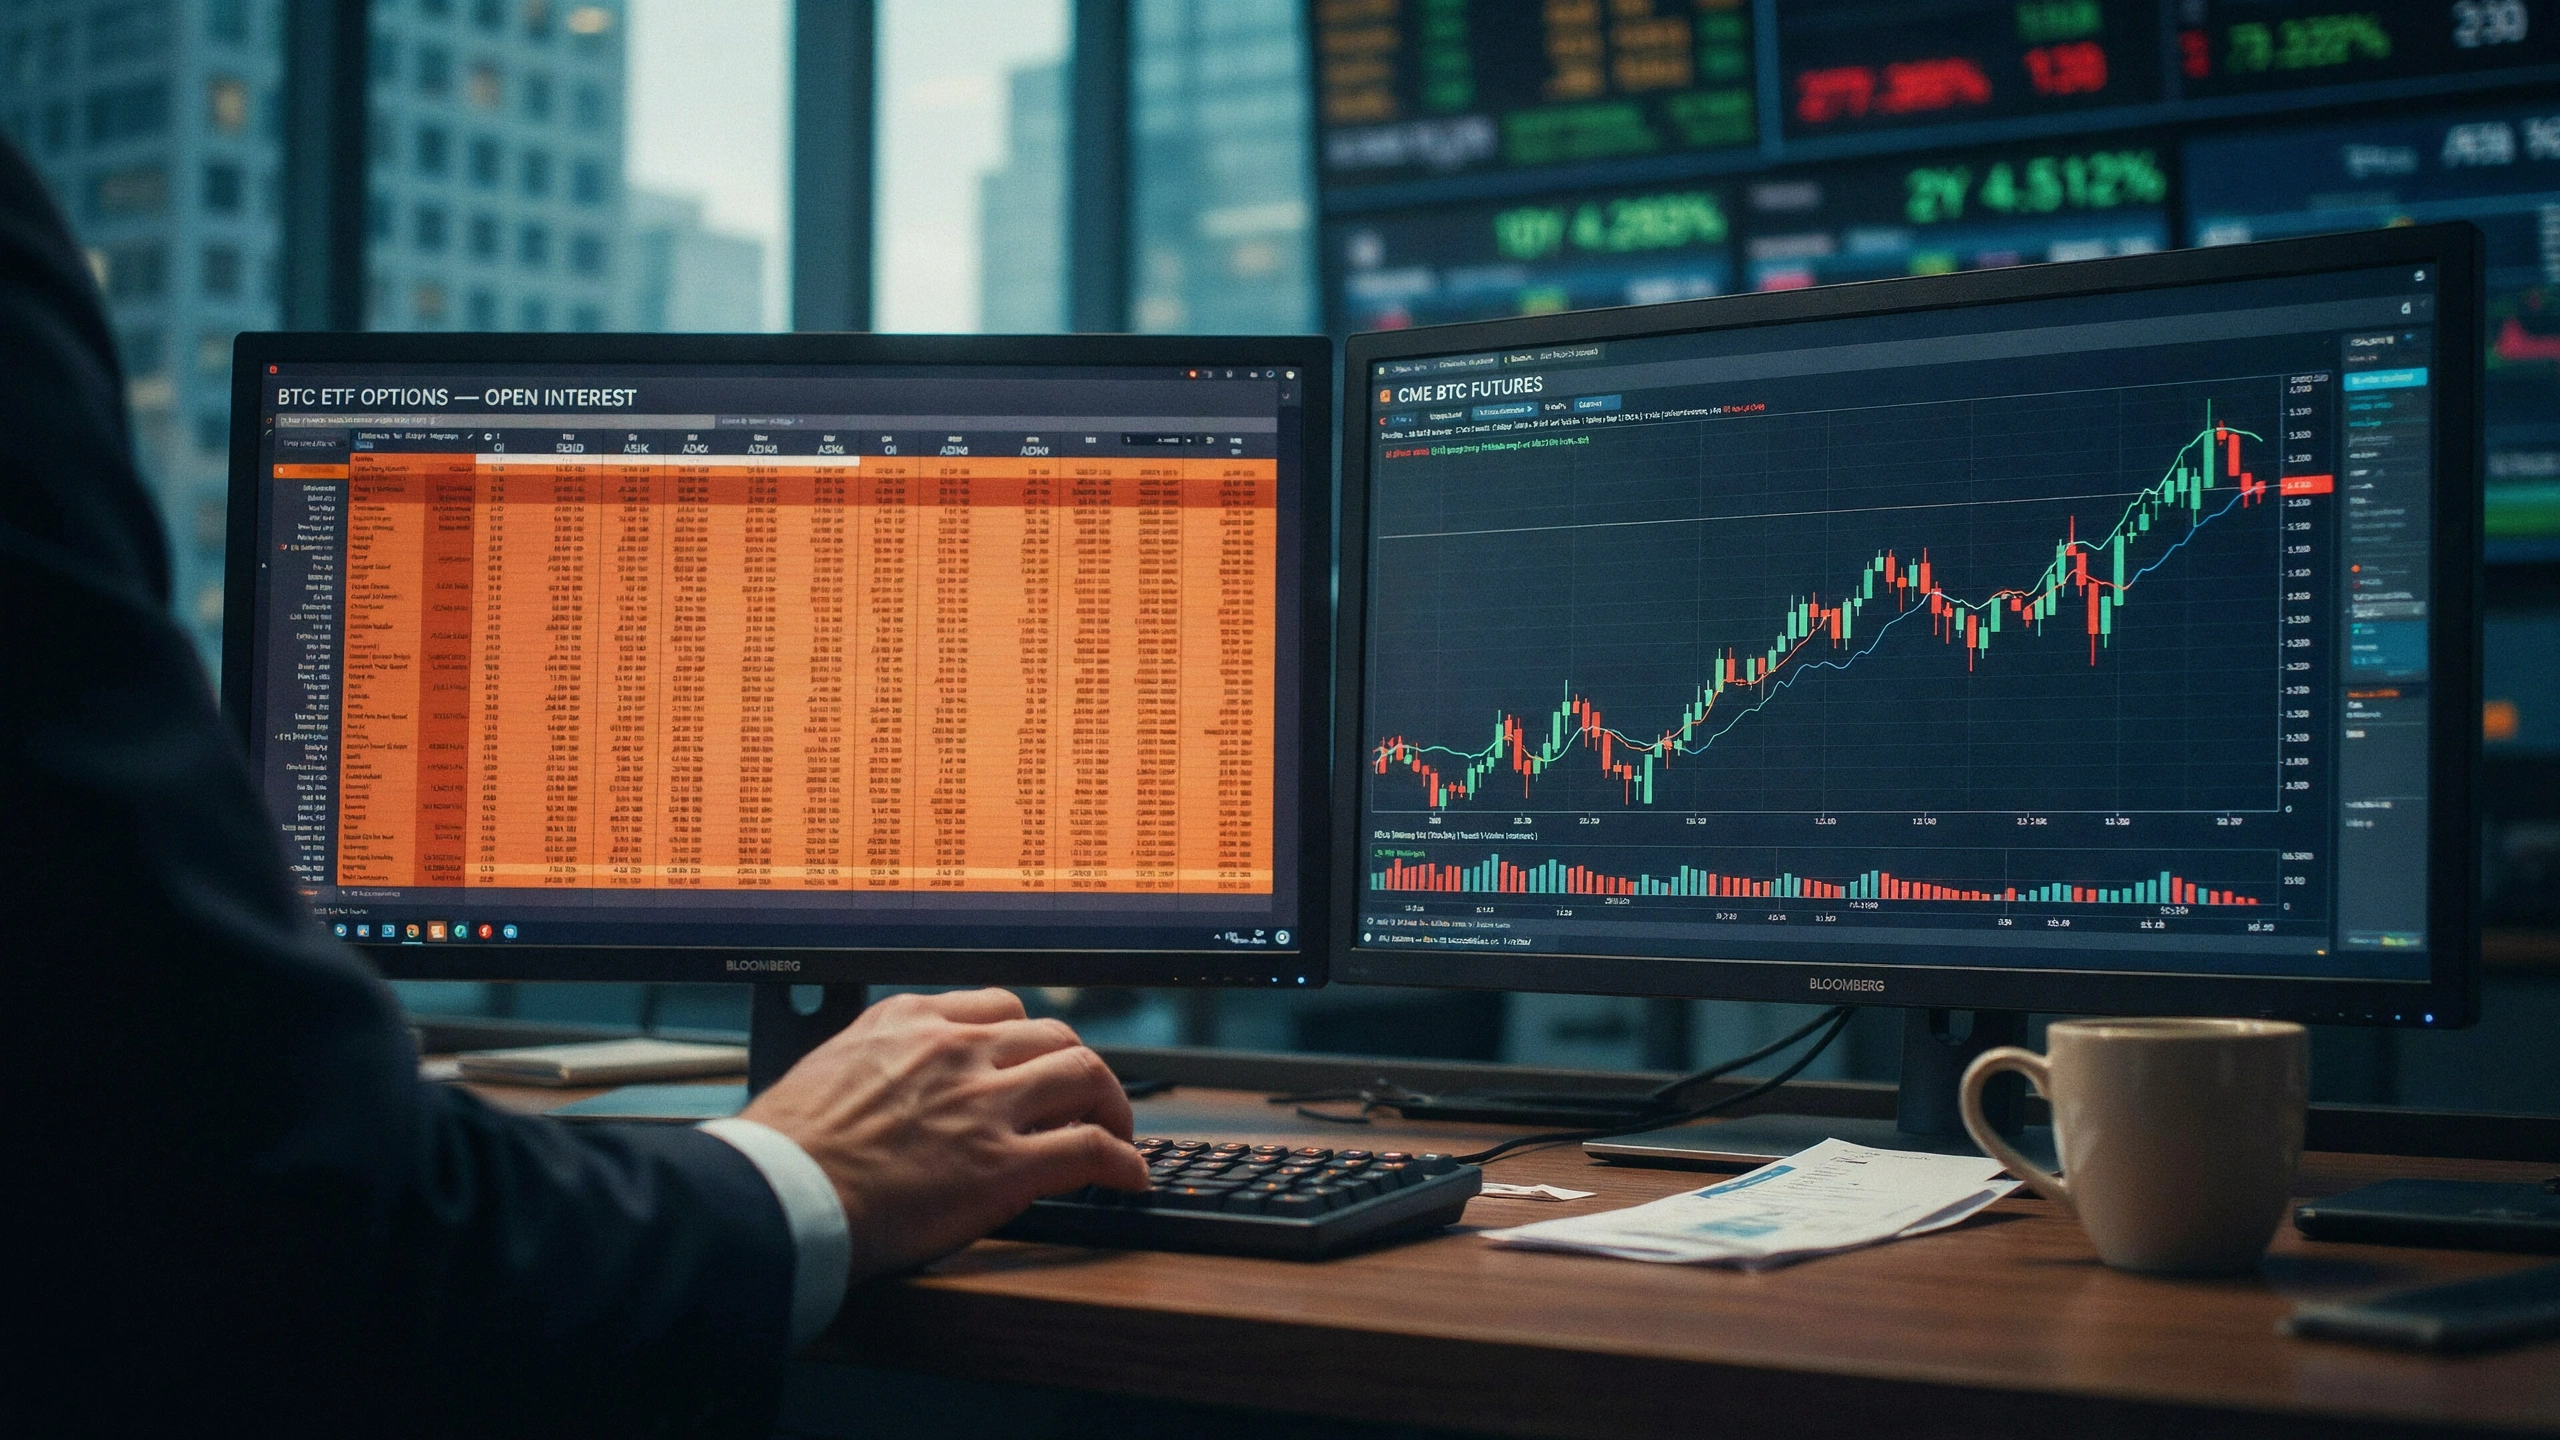
The marginal price-setter for bitcoin is no longer a crypto exchange but a CME clearinghouse, and that means every basis-point move in Treasury yields now transmits directly into your spot bitcoin usd holdings.
A decisive reclaim of $82,500 on rising ETF options call volume would force CME dealers to hedge gamma, creating a mechanical bid that could propel bitcoin toward the $85,000 Polymarket consensus target. Sectors benefiting include bitcoin ETF issuers, regulated custody providers, and CME-listed crypto derivatives desks.
A sustained break below $79,000 would trigger a cascade of ETF options delta-hedging sales, while the 10-year Treasury at 5.045% continues to drain liquidity from risk assets. Vulnerable classes include high-beta crypto miners, unhedged spot bitcoin eur holders, and leveraged perp longs on offshore venues.
📄 Leer informe completo (expandir)
- What Happened: Bitcoin fell 2.08% to $79,977 as spot bitcoin ETF options volume hit an all-time record and CME open interest overtook Deribit for the first time, marking a regime shift in who controls crypto price discovery.
- Hidden Mechanism: Regulated dealers on CME are now hedging their options books with spot bitcoin, meaning their delta-hedging flows mechanically amplify moves in both directions and turn the $80,000 strike into a gamma battleground.
- Capital Transmission: Capital is rotating out of offshore perpetual swaps and into CME-listed options, draining liquidity from crypto-native venues and transmitting every basis-point move in the 10-year Treasury yield directly into spot bitcoin usd pricing.
The $80,000 Gamma Trap: Why Bitcoin Is Dropping Today
Bitcoin is dropping because the market just crossed a structural threshold: CME open interest in bitcoin options has overtaken Deribit for the first time, and the $80,000 strike is now the most heavily populated options line in the market. When dealers are short gamma at a round number like $80,000, they are forced to sell spot bitcoin as price falls toward it and buy as it rises away — a mechanical process that amplifies volatility rather than dampening it. In plain English: the people who sold those options are now forced to chase the market in whichever direction it moves, and right now they are chasing it lower.
The immediate catalyst is the record volume in spot bitcoin ETF options. These are not retail lottery tickets; they are institutional hedging instruments used by asset managers who hold bitcoin etf shares and want to protect their downside. When those managers buy puts, the dealers who sell them must short bitcoin to stay neutral. That selling pressure hit the spot market today, pushing bitcoin usd below the $80,000 psychological line and dragging bitcoin eur and bitcoin today price quotes down across every venue.
Why Bitcoin Is Down While the S&P 500 Grinds Higher
The S&P 500 is up 0.28% today, and bitcoin is down 2.08%. That divergence is the tell. The 10-year Treasury yield at 5.045% is sucking capital out of anything that does not pay a coupon, and bitcoin — which pays nothing — is the first asset to feel the drain. The yield curve has normalized to a positive 1.05% spread between the 10-year and the 3-month bill, which sounds technical but simply means the bond market is no longer paying you to hide in short-dated paper; it is paying you to take duration risk. That is competition for bitcoin, and it is winning right now.
The Fed funds target at 5.25%–5.50% with an effective rate of 5.33% means the risk-free alternative to bitcoin is yielding more than 5%. Polymarket traders price a 76.5% chance of another 25 basis point increase in December. Every basis point higher is another basis point of opportunity cost for holding bitcoin, and the market is repricing that reality in real time.
Positioning & Liquidity Map: Who Is Trapped?
The trapped cohort is the offshore leveraged long. Retail and crypto-native funds who bought perpetual swaps on Deribit and other venues at $82,000–$85,000 are now underwater, and their liquidation clusters sit at $78,500 and $77,200. As CME dealers sell spot to hedge their gamma, they push the market toward those liquidation levels, which triggers forced selling from the perp longs, which pushes the market lower still. It is a doom loop with a clearinghouse at the center.
The marginal buyer right now is the CME options dealer who is short gamma and must buy spot as price falls to stay delta-neutral — but only below the strike, and only until their gamma exposure flips. Above $82,500, those same dealers become buyers, which is why the upside tail is so violent. The marginal seller is the ETF options hedger who is buying puts and forcing dealers to short. The mempool backlog of 55,143 unconfirmed transactions with a fastest fee of 12 sat/vB tells you on-chain activity is not the driver; this is a derivatives market story, not a blockchain story.
Forward Scenarios & Probability Matrix
| Scenario | Implied Probability | Key Trigger / Level | Expected Asset Reaction |
|---|---|---|---|
| Base Case | 55% | Bitcoin holds $79,000 and CME gamma stabilizes | Chop between $79,000 and $82,500 as dealers hedge; bitcoin etf flows turn neutral |
| Bullish Tail | 25% | Reclaim of $82,500 forces dealer gamma flip | Short squeeze toward $85,000 Polymarket target; bitcoin atm volumes spike as retail FOMOs back in |
| Bearish Stress | 20% | Break below $78,500 triggers perp liquidations | Cascade to $77,200; ETF options delta-hedging accelerates the sell; bitcoin today news turns ugly |
Dorian Reed
Computational Econometrician. Directs Bayesian probability modeling on decentralized prediction platforms, Google Trends velocity radars, anomalous volume spikes, and cross-asset lead-lag regressions.