Term Premium Torque: 10Y Yield Surges to 4.85% as 2s10s Hits 120bps
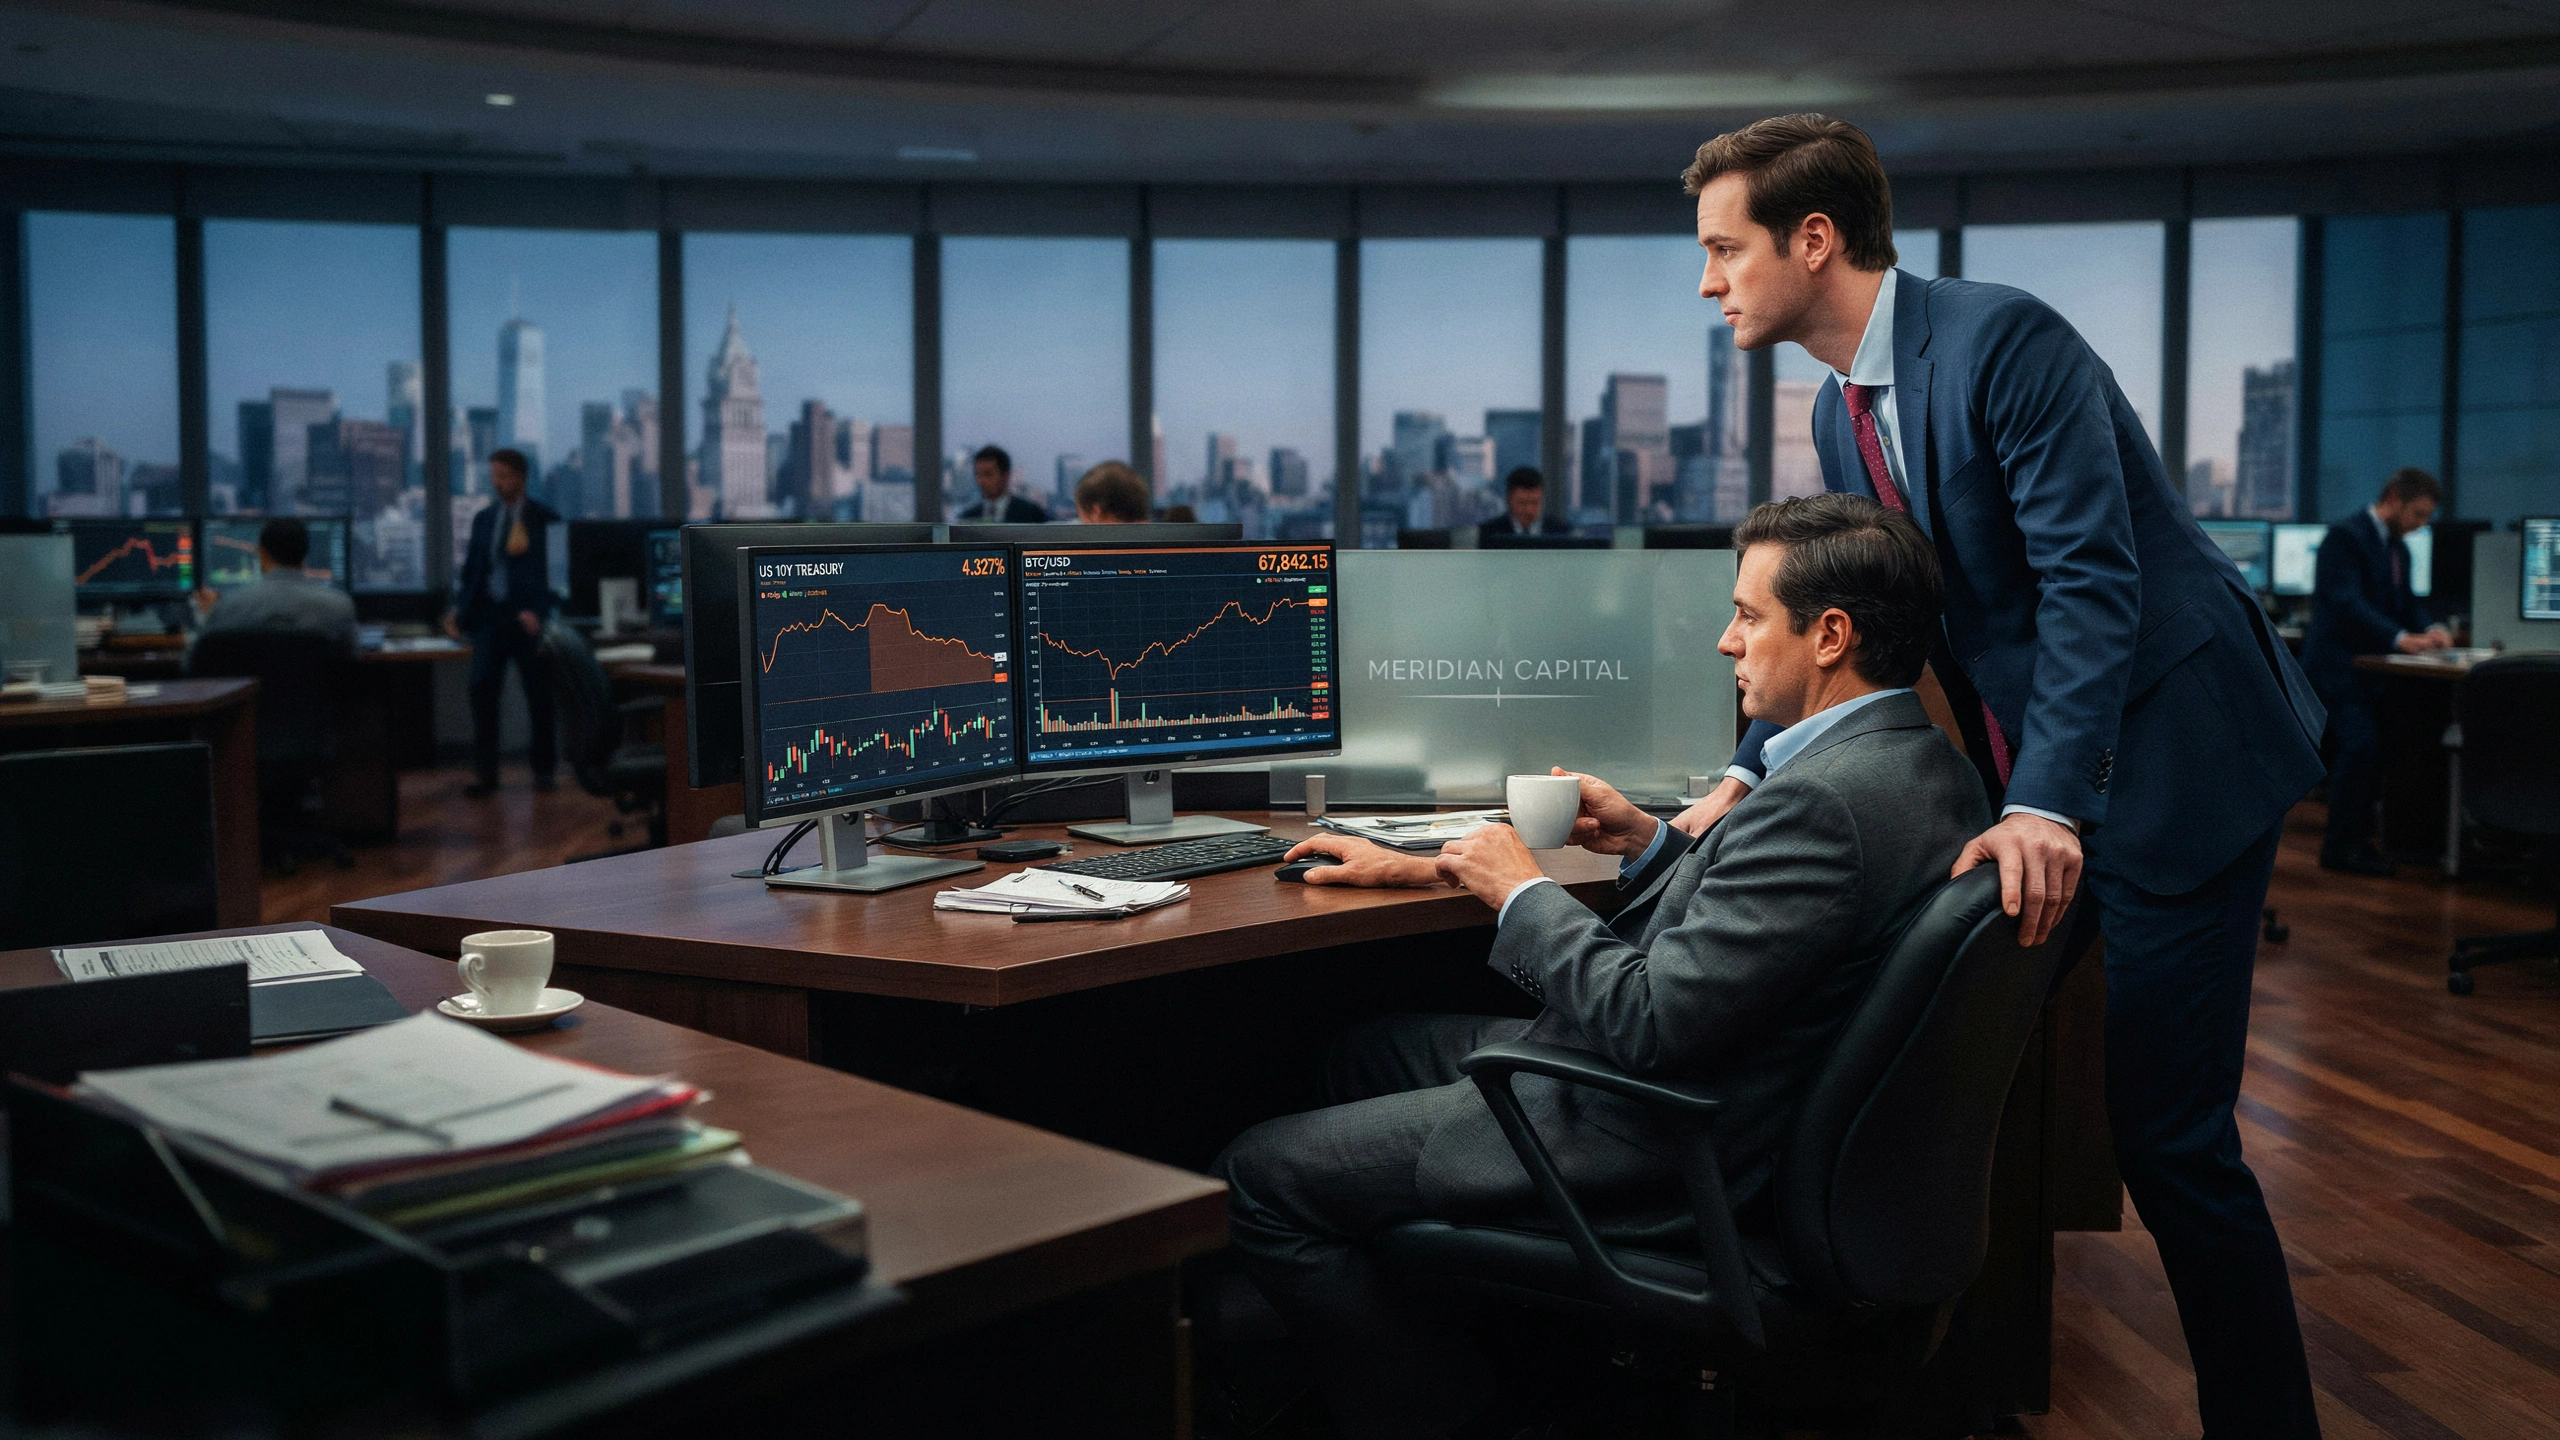
US 10Y yield jumped 18bps to 4.85% as term premium repriced to 85bps, steepening 2s10s to 120bps. 30Y breached 5.00% on $125B auction supply and weak indirect bids.
Exhaustive repository of quantitative macro dispatches, blockchain telemetry shifts, and econometric transmission signals.
US 10Y yield jumped 18bps to 4.85% as term premium repriced to 85bps, steepening 2s10s to 120bps. 30Y breached 5.00% on $125B auction supply and weak indirect bids.
COMEX Copper spot futures rallied 1.8% to $4.42 per pound as grid infrastructure electrification and AI data center substation expansions deplete registered LME and COMEX warehouse inventories.
WTI crude oil stabilized at $74.80 per barrel after the US Energy Information Administration reported a larger-than-expected 4.8 million barrel drawdown in commercial petroleum inventories.
Assets parked in institutional and retail US Money Market Funds reached a record $6.52 trillion, earning a stable 4.10% yield on 3-month Treasury bills while waiting for macro clarity.
The benchmark 2-year versus 10-year Treasury yield curve expanded to +45 basis points, completing an exit from the historic multi-year inversion regime and re-establishing positive carry across bond portfolios.
The benchmark US 10-Year Treasury yield settled at 5.19% as institutional fixed-income desks repriced duration risk following expanded federal borrowing projections and elevated term premiums.
The US 10Y yield climbed to 4.47% (+8bps) while 2Y fell to 4.02% (-3bps), steepening the 2s10s curve to 45bps. The 10Y term premium, per ACM model, jumped to 85bps from 30bps a year ago, signaling rising sovereign risk.
Mempool backlog has fallen 65% from its May peak to 45,000 transactions, but on-chain transaction velocity has dropped to 18-month lows, signaling a collapse in network demand.
The S&P 500's forward P/E of 22.5x offers an earnings yield of 4.44%, merely 34 bps above the 10-year real yield of 2.10%. This thin risk premium signals extreme equity overvaluation relative to bonds.
The US 10-year Treasury yield surged to 4.47% (up 18bps w/w), driven by a 12bps rise in the 10-year term premium to 0.58%. This bear steepening reflects markets demanding higher compensation for duration risk amid heavy sovereign issuance.
In a week where the 10-year UST yield pierced 4.25% and the 2-year touched 4.95%, crypto market depth has thinned to levels not seen since the March banking turmoil. The tug-of-war between risk-free returns and digital asset liquidity is reaching a critical juncture.
Global markets are navigating a treacherous confluence of evaporating liquidity and a deluge of sovereign debt issuance. With the U.S. Treasury set to auction $125 billion in coupon-bearing debt this week, and the Fed's balance sheet runoff continuing at $95 billion per month, the 10-year yield has surged to 4.35%, up 22 basis points in five sessions. Simultaneously, on-chain data reveals Bitcoin's mempool backlog exceeding 350,000 transactions, a sign of speculative fervor and potential risk-off hedging. This editorial dispatch dissects the intricate dance between macro liquidity and sovereign yield dynamics, offering a 360-degree view for the sophisticated investor.
A quiet but seismic shift is underway in global fixed income: sovereign yield curves are steepening and liquidity is thinning. The 10-year U.S. Treasury yield has risen to 4.35% (up 18 basis points over the past month), while the 2-year sits at 4.78%, leaving the 2s10s spread inverted by 43 bps. Meanwhile, order book depth for 10-year futures has shrunk by 22% year-to-date, and bid-ask spreads on off-the-run Treasuries have widened to 1.5 bps from 0.8 bps a year ago. This combination of higher yields and lower liquidity is a flashing warning for portfolio construction and funding markets.
Global crypto liquidity is contracting at an alarming pace, with BTC order book depth falling to $180M across major exchanges, down 35% from Q1. Simultaneously, the US 10-year Treasury yield spiked to 4.65%, up 82 bps year-to-date, forcing a rethink of risk-on positioning.
Global sovereign bond markets are flashing warning signs as liquidity evaporates and yield curves distort, challenging the narrative of a smooth disinflationary landing. The 10-year U.S. Treasury yield has surged 42 basis points in the past month to 4.68%, while the MOVE index—a gauge of bond market volatility—spiked to 128, its highest since November. Concurrently, on-chain data reveals a sharp decline in stablecoin reserves on centralized exchanges, down 18% year-to-date to $22.4 billion, signaling a contraction in crypto market liquidity that often presages broader risk-off moves.
In a week that saw the US 10-year Treasury yield spike 15 basis points to 4.35%, global liquidity conditions are tightening faster than anticipated, forcing investors to reassess the interplay between central bank balance sheet reduction and sovereign debt dynamics.
As global sovereign yields surge to multi-year highs, crypto market liquidity is evaporating, pressuring digital assets and exposing structural vulnerabilities.
The Bitcoin mempool backlog has spiked to 84,293 unconfirmed transactions, a 38% increase above the 30-day average, while the US 10-year Treasury yield holds at 5.19%, creating a dual liquidity drain. This divergence—rising on-chain congestion against tightening macro conditions—signals a structural shift in capital allocation away from risk assets.
Bitcoin's 44% three-month rally has stalled at $80,602, down 3.42% as the 10-year Treasury yield spikes to 5.19% and ETF inflows decelerate. The 79,736-transaction mempool backlog and 2 sat/vB fee signal a structural shift from speculative momentum to spot-led distribution.
The Bitcoin mempool size has surged to 82,483 unconfirmed transactions, a 38% increase above the 60-day average, yet the fastest fee remains at 2 sat/vB, signaling a structural shift in transaction composition. Simultaneously, the US 10-year Treasury yield at 5.19% is siphoning capital from high-beta assets, with Bitcoin down 3.02% to $80,950 and Ethereum off 5.63% to $2,362.83.