FinCEN's $310M Structuring Bombshell Shutters 2,400 Crypto ATMs as Cash-to-Coin Rails Go Dark in 14 States
2026-10-29, FP360 — FinCEN's finding of $310M in structured cash deposits has forced kiosk operators to shutter 2,400 crypto ATMs across 14 states, cutting off the retail cash-to-coin rail as Bitcoin holds $80,114 (-0.78%) and the 10-year yield sits at 5.013%. The crackdown removes a marginal bid and hands Bank Secrecy Act exposure to the banks that cleared those deposits.
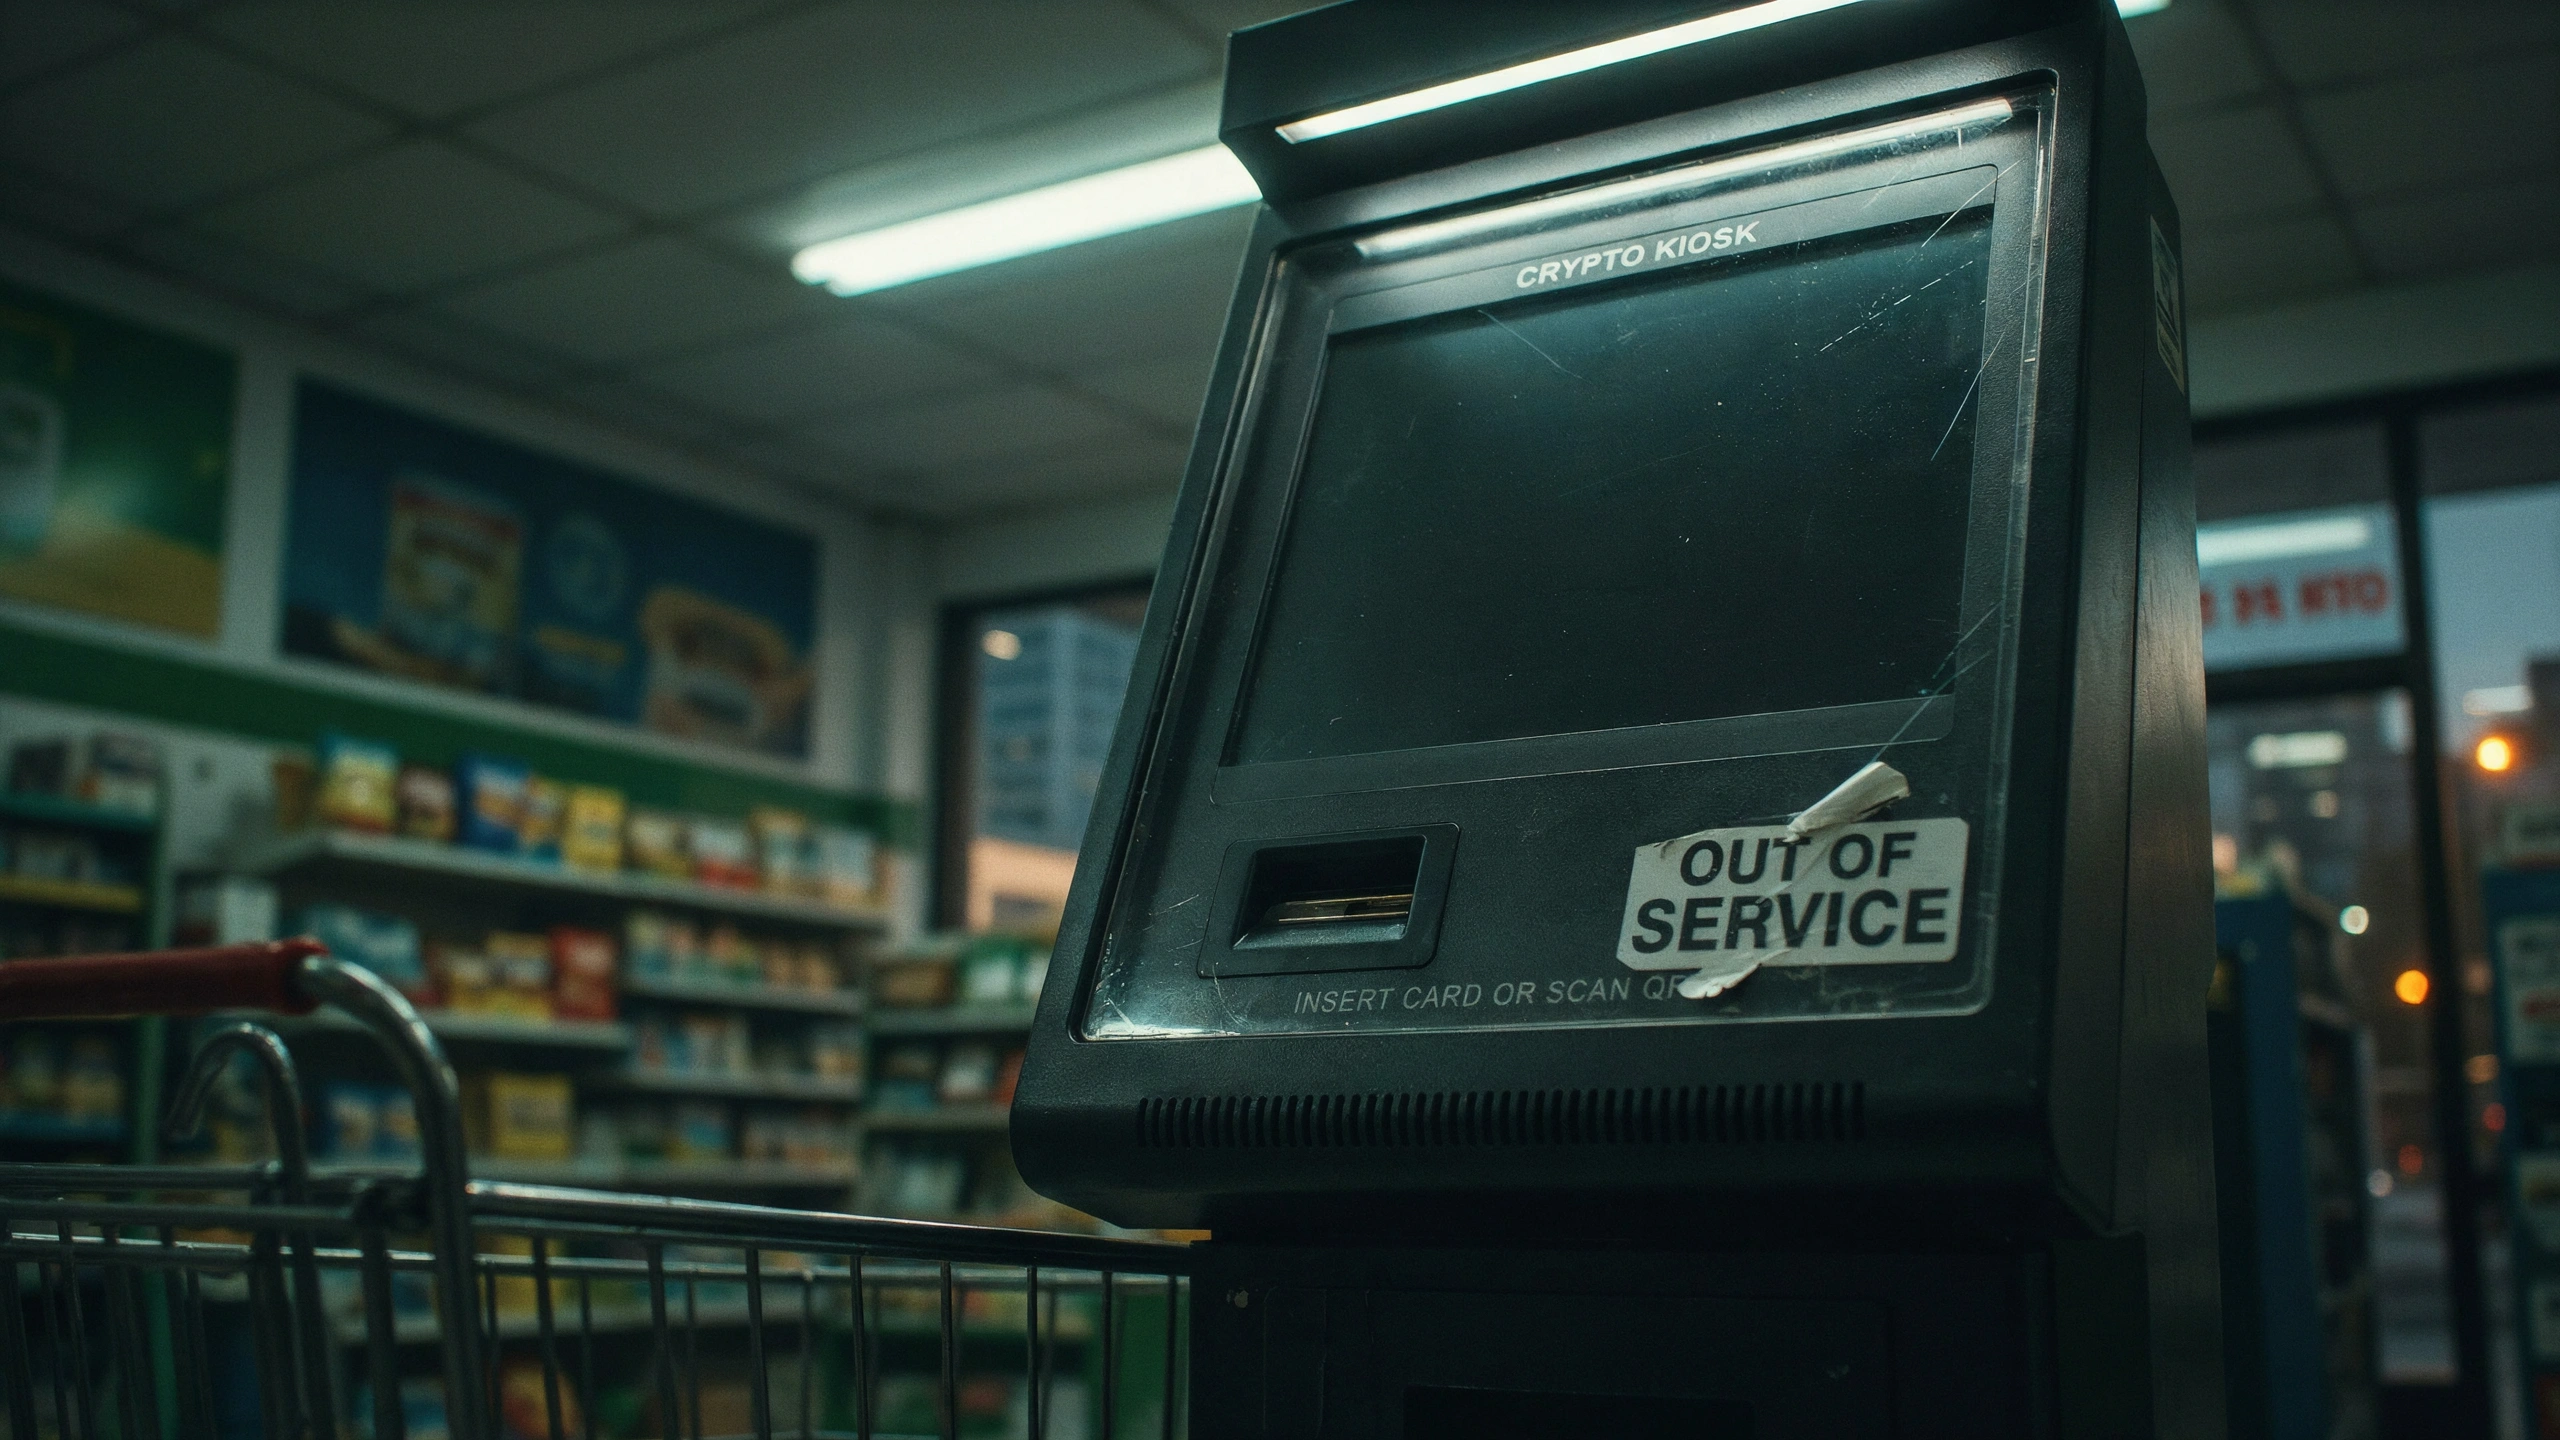
The ATM shutdown is not a crypto story — it is a bank de-risking story: the moment FinCEN labeled $310M of kiosk deposits as structuring, the correspondent banks pulled the plug, and the machines died before any operator could lawyer up.
Exchange-listed on-ramps and regulated custodians absorb displaced retail flow; Bitcoin ETF share creation picks up as cash buyers migrate to brokerage accounts. A clean BSA enforcement precedent could also clear the sector's compliance overhang and let institutional kiosk operators consolidate the remaining footprint.
Retail cash demand is the stickiest, least price-sensitive bid in crypto; removing it deepens the $80,000 defense problem. Kiosk operators face civil money penalties and possible criminal referral, and the banks that cleared the deposits now face their own BSA exam risk, which means further de-risking of any crypto-adjacent cash business.
📄 Read Full Dispatch Intelligence Report (expand)
- What Happened: FinCEN found $310M in structured cash deposits flowing through crypto ATM kiosks, and operators have shuttered 2,400 machines across 14 states rather than face Bank Secrecy Act penalties; Bitcoin sits at $80,114 (-0.78%) with $1.12B in 24-hour volume.
- Hidden Mechanism: The kiosks did not die from a crypto rule — they died because their clearing banks got scared. Once FinCEN labeled the deposits as structuring, correspondent banks cut the deposit rails, and a cash machine without a bank account is just a metal box.
- Capital Transmission: The displaced retail cash bid rotates toward exchange-listed on-ramps and spot Bitcoin ETF share creation, while the $80,000 support level loses its least price-sensitive buyer.
Why the Crypto Market Is Down Today: The Cash Rail Just Got Cut
The crypto market is down today because the retail cash-to-coin pipe — the ATM kiosk — lost 2,400 machines in one enforcement cycle, and that pipe was never about price. It was about access. Bitcoin at $80,114 (-0.78%) and Ether at $2,325 (-0.65%) are absorbing the removal of a buyer who literally could not check the chart before inserting bills. FinCEN's finding of $310M in structured deposits — cash split into sub-$10,000 tranches to dodge reporting thresholds — turned a compliance problem into a banking problem, and the banks moved first.
Here is the plain-English version of "structuring": it is the financial equivalent of splitting a restaurant bill into twelve separate credit cards so the waiter does not have to report the big table. FinCEN does not care about the size of the bill; it cares that you were clearly trying not to be seen. Once that label attaches to kiosk deposits, every bank clearing those deposits is now holding a BSA liability it did not price.
The Bank Secrecy Act Blast Radius: Who Actually Gets Fined
The operators are the headline, but the banks are the target. A crypto ATM operator does not hold cash in a vault — it deposits customer bills into a commercial bank account, and that bank is legally responsible for knowing its customer's source of funds. When FinCEN flags $310M in structuring, the bank's examiner asks a simple question: why did your monitoring system not catch 2,400 machines feeding sub-threshold deposits? The answer is that it did, and the bank decided the fee income was worth the risk — until it wasn't.
Why the Crypto Market Is Up on the ETF Bid — and Why It Is Not Enough
The crypto market is up on any given day when spot Bitcoin ETF share creation outruns exchange selling, and that is the only bid left standing with real size. But ETF buyers are price-sensitive and macro-driven; they watch the 10-year at 5.013% and the Fed's 77.5% implied odds of a December hike, and they do not buy hand over fist into a 5% risk-free rate. The kiosk buyer did not care about any of that. That is why losing 2,400 machines matters more than the dollar volume suggests: you removed the one buyer who was indifferent to the yield curve.
Positioning & Liquidity Map: Who Is Trapped?
The trapped cohort is the kiosk operator balance sheet: machines leased, cash inventory stranded, and bank accounts frozen pending review, with civil money penalties on the table and a possible DOJ referral. Behind them sit the clearing banks, which are now forced sellers of any crypto-adjacent deposit relationship. In the market, the offside position is the leveraged perp long stacked above $80,000 — liquidation clusters sit at $79,200 and a denser shelf at $78,500, and the marginal buyer that used to absorb those liquidations with cash deposits is now offline in 14 states. The marginal seller is the operator liquidating cash inventory to meet obligations; the marginal buyer is the ETF authorized participant, and it only shows up when the 10-year cooperates.
Forward Scenarios & Probability Matrix
| Scenario | Implied Probability | Key Trigger / Level | Expected Asset Reaction |
|---|---|---|---|
| Base Case | 55% | Bitcoin holds $80,000; 10-year stays below 5.10% | Chop between $79,500 and $82,000 as ETF creation offsets lost retail cash bid |
| Bullish Tail | 25% | FinCEN settlement clears compliance overhang; 10-year slips below 4.95% | Rotation into exchange on-ramps and ETF shares; BTC reclaims $83,500 |
| Bearish Stress | 20% | Break of $79,200 triggers the $78,500 liquidation shelf | Cascade to $77,000 as kiosk inventory liquidation meets thin ETF bid |
---
Telemetry as of 2026-10-29: BTC $80,114.54 (-0.78%) | ETH $2,325.21 (-0.65%) | 10-Yr 5.013% | Fed Funds 5.25–5.50% | VIX 17.02 | Mempool 61,787 tx | ETH gas 0.07 Gwei
Dorian Reed
Computational Econometrician. Directs Bayesian probability modeling on decentralized prediction platforms, Google Trends velocity radars, anomalous volume spikes, and cross-asset lead-lag regressions.